Essential Home Buying Criteria for First-Time Buyers in Sarasota
Buying your first home in Sarasota, Florida, is a significant milestone that requires careful planning and local expertise. The Gulf Coast market is dynamic, with unique challenges regarding flood zones, insurance costs, and inventory levels that differ sharply from other regions. According to recent market analyses, the median home price in Sarasota has seen substantial shifts, making it critical for new buyers to understand the financial and structural criteria before making an offer. This guide outlines the essential steps and considerations to help you navigate the Sarasota real estate landscape with confidence. (Meet Carolyn Yates Your)
Financial Preparation and Mortgage Readiness
Before you begin viewing properties, securing your financial foundation is the most critical step. First-time buyers often underestimate the total cost of homeownership, which extends far beyond the down payment. In Sarasota, where property values have appreciated significantly, having a robust financial buffer is essential.
Down Payment and Closing Costs
While many loan programs allow for down payments as low as three percent, closing costs in Florida typically range from two to five percent of the purchase price. These fees include title insurance, recording fees, and transfer taxes. For a median-priced home in the area, these costs can amount to tens of thousands of dollars. It is vital to calculate these upfront to avoid last-minute funding issues.
Debt-to-Income Ratio Requirements
Lenders generally require a debt-to-income (DTI) ratio below 43 percent, though some prefer lower ratios for better interest rates. This ratio compares your monthly debt obligations to your gross monthly income. If you have existing student loans, car payments, or credit card debt, paying these down before applying for a mortgage can significantly improve your loan terms. A lower DTI signals to lenders that you are a low-risk borrower, which is particularly important in a market with rising interest rates.
Pre-Approval vs. Pre-Qualification
Always obtain a formal pre-approval letter rather than just a pre-qualification. Pre-approval involves a thorough review of your credit history, income verification, and asset documentation. In competitive Sarasota neighborhoods, sellers often require pre-approved offers to ensure the buyer is serious and financially capable. This document strengthens your position when making an offer on a home.
Location Strategy: Neighborhoods and Commutes
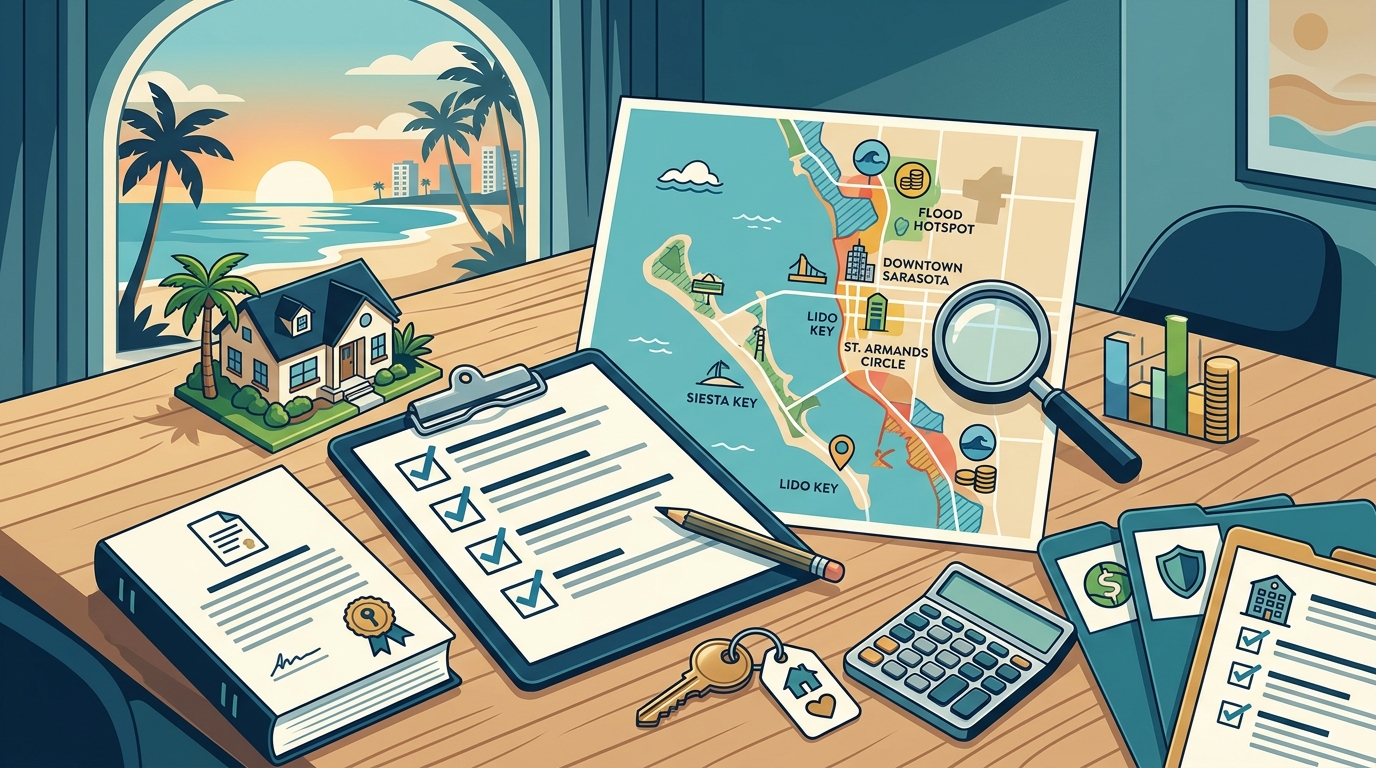
Sarasota is not a monolithic market. It consists of distinct communities, each with its own character, price point, and lifestyle benefits. Understanding these differences is key to finding a home that fits your long-term goals.
Urban Living vs. Suburban Quiet
Downtown Sarasota offers walkable urban living with access to theaters, restaurants, and cultural events. However, these properties often come with higher HOA fees and smaller lot sizes. In contrast, suburban areas like North Port or Parrish offer more space and lower entry prices but require longer commutes to the city center. Buyers must weigh the value of convenience against the cost of space.
Coastal Proximity and Water Access
Proximity to the Gulf of Mexico is a major driver of property values in Sarasota. Homes on Nokomis Beach or Siesta Key command premium prices due to their desirability and limited inventory. However, being near the water also introduces specific regulatory and insurance challenges. Buyers should consider whether they want direct beach access, water views, or simply a short drive to the coast.
Emerging Neighborhoods
Areas like Osprey and Venice are seeing increased development and interest from first-time buyers looking for more affordable entry points. These neighborhoods often offer newer construction and modern amenities. Researching local development plans can help identify areas with potential for future appreciation.
Structural Integrity and Flood Zone Analysis
Florida's climate and geography present unique structural challenges that first-time buyers must address. Ignoring these factors can lead to costly repairs and insurance nightmares.
Flood Zone Designations
Most of Sarasota County is located in or near a Special Flood Hazard Area (SFHA). Properties in Zone AE or VE require mandatory flood insurance, which can cost thousands of dollars annually. Before making an offer, verify the property's flood zone designation using FEMA maps. A home just outside a flood zone can save you significant money over the life of the mortgage.
Roof and Foundation Age
Florida's humidity and salt air accelerate wear on building materials. The roof is often the most expensive component to replace, and many insurance companies require roofs to be less than 15 years old to issue a policy. Additionally, foundation issues are common in areas with sandy soil or high water tables. A thorough structural inspection is non-negotiable to identify potential settling or moisture intrusion.
Impact-Resistant Windows and Doors
Florida building codes have evolved to require impact-resistant windows and doors in many coastal counties. If a home was built before these mandates, upgrading these features may be necessary for insurance discounts and hurricane protection. Verify the age and certification of existing windows to avoid unexpected renovation costs.
Understanding Insurance and Maintenance Costs
Homeowners insurance in Florida has risen dramatically in recent years due to increased claim frequencies and litigation costs. This is a critical factor in your monthly housing budget.
Windstorm and Hurricane Coverage
Standard homeowners policies in Florida often exclude windstorm damage, requiring a separate policy or a high deductible. In Sarasota, windstorm insurance can add thousands to your annual premium. Some insurers require specific roof certifications or impact-resistant features to offer coverage. Shop around multiple carriers to find the best rates, as premiums can vary widely.
HOA Fees and Restrictions
Many Sarasota communities, especially those near the water, have Homeowners Associations (HOAs). These fees cover maintenance of common areas, security, and amenities. However, HOAs also impose restrictions on renovations, rentals, and even exterior colors. Review the HOA documents carefully to ensure they align with your lifestyle and financial plans.
Maintenance of Coastal Properties
Coastal homes require more frequent maintenance due to salt corrosion and humidity. HVAC systems, in particular, work harder in Florida's climate and may need more frequent servicing. Budget for regular upkeep to preserve the home's value and prevent minor issues from becoming major repairs.
Negotiation Tactics in a Competitive Market
Sarasota's real estate market can be highly competitive, with desirable homes receiving multiple offers. Effective negotiation strategies are essential to securing your dream home.
Understanding Market Conditions
In a seller's market, homes may sell above asking price and close quickly. In a buyer's market, there is more room for negotiation on price and repairs. Work with a local agent who can provide real-time data on days on market and sale-to-list price ratios for your target neighborhoods.
Contingencies and Inspection Waivers
While it is tempting to waive contingencies to make an offer more attractive, this carries significant risk. Keeping the inspection contingency allows you to back out or negotiate repairs if major issues are found. Consider a "repair credit" negotiation instead of a full waiver, which protects you without appearing risky to the seller.
Closing Timeline Flexibility
Sellers often prefer buyers who can accommodate their closing timeline. If you can offer a rent-back agreement or a flexible closing date, it may make your offer more appealing than a higher bid with rigid terms. This flexibility can be a decisive factor in a multiple-offer scenario.
Key Takeaways
- Financial Buffer: Budget for closing costs of 2-5% and maintain a reserve for immediate repairs.
- Flood Zones: Verify FEMA flood zone designations to anticipate insurance costs and regulatory requirements.
- Insurance Costs: Obtain multiple quotes for windstorm and homeowners insurance before making an offer.
- Local Expertise: Work with a local agent who understands neighborhood-specific nuances and market trends.
- Structural Checks: Prioritize roof age, foundation integrity, and impact-resistant features in your inspection.
- HOA Review: Carefully review HOA fees, restrictions, and financial health before purchasing in a community.
- Pre-Approval: Secure a formal pre-approval letter to strengthen your negotiating position.
Frequently Asked Questions
What is the average down payment for first-time buyers in Sarasota?
While some loan programs allow down payments as low as 3%, it is advisable to save at least 5-10% to cover closing costs and reduce monthly mortgage payments. First-time buyer programs in Florida may offer down payment assistance grants.
How much does flood insurance cost in Sarasota?
Flood insurance costs vary based on the property's flood zone, elevation, and construction type. Homes in high-risk zones (AE or VE) can expect to pay between $1,500 and $5,000 or more annually. Properties outside these zones may have lower premiums.
Are there first-time home buyer programs in Sarasota County?
Yes, Sarasota County and the state of Florida offer various down payment assistance programs and favorable loan terms for first-time buyers. These programs often have income and purchase price limits. Consulting with a local lender can help you identify eligible options.
What is the best time of year to buy a home in Sarasota?
The winter months (December to March) are peak season for real estate in Sarasota, leading to higher competition and prices. The summer and early fall often see less inventory but also fewer buyers, potentially offering more negotiation leverage.
How important is the home inspection in Florida?
A home inspection is critical in Florida due to the state's unique climate and building materials. It helps identify issues with roofs, foundations, plumbing, and electrical systems that may not be visible during a walkthrough. Never waive the inspection contingency without professional advice.
What are the closing costs in Florida?
Closing costs in Florida typically range from 2% to 5% of the purchase price. These include title insurance, recording fees, transfer taxes, and lender fees. In some cases, sellers may agree to pay a portion of the closing costs as a concession.
How do I find a good real estate agent in Sarasota?
Look for an agent with extensive local experience, strong client reviews, and a track record of working with first-time buyers. Ask about their knowledge of specific neighborhoods, flood zones, and current market conditions. Carolyn Yates, a Sarasota-based agent, specializes in helping buyers navigate these complexities with precision pricing and expert positioning.
Start Your Home Search
Navigating the Sarasota real estate market requires more than just financial readiness; it demands local insight and strategic guidance. Whether you are looking for a coastal retreat or a suburban family home, having a dedicated professional by your side can make the difference between a stressful experience and a successful purchase. Carolyn Yates offers a data-driven approach to home buying, ensuring you find a property that meets your criteria and budget. Visit the Home Valuation page to understand market trends, or explore the Blog for the latest neighborhood insights. For personalized assistance, contact Carolyn Yates today to schedule a consultation and begin your journey to homeownership.